The MSF Basic RiderCourse and Insurance: What’s Real About the Discount
Everyone says the MSF course gets you an insurance discount. The course is genuinely worthwhile — but the discount varies by insurer, isn't universal, and is never a fixed percentage. Here's the honest breakdown.
Take the MSF course and your insurance gets cheaper — that’s the folk wisdom, and it’s mostly true: right in outline, wrong in the details. The Motorcycle Safety Foundation’s Basic RiderCourse is genuinely valuable training, and the insurance benefit is real at many insurers. But it is not universal, not automatic, and not a fixed percentage. Here’s the reality.
Key takeaways
The BRC is real training — classroom plus on-bike range instruction — and its safety value stands on its own.
Many insurers recognize training with a discount or favorable rating factor, but recognition is not universal.
No fixed discount percentage exists across the industry. Any specific number you read is someone’s deal, not a rule.
Confirm with your insurer before enrolling — ask which courses count and how the credit applies.
In many states, BRC completion can waive the riding skills test for your license endorsement — a separate, practical benefit that also varies by state.
The Motorcycle Safety Foundation (MSF) is the US’s best-known rider education organization, and its Basic RiderCourse (BRC) is the standard entry point for new riders. In general terms, the course has two halves:
Classroom instruction covers the mental side of riding: risk awareness, protective gear, how motorcycles handle differently from cars, strategies for intersections and curves, and riding impaired — the judgment curriculum that keeps riders alive.
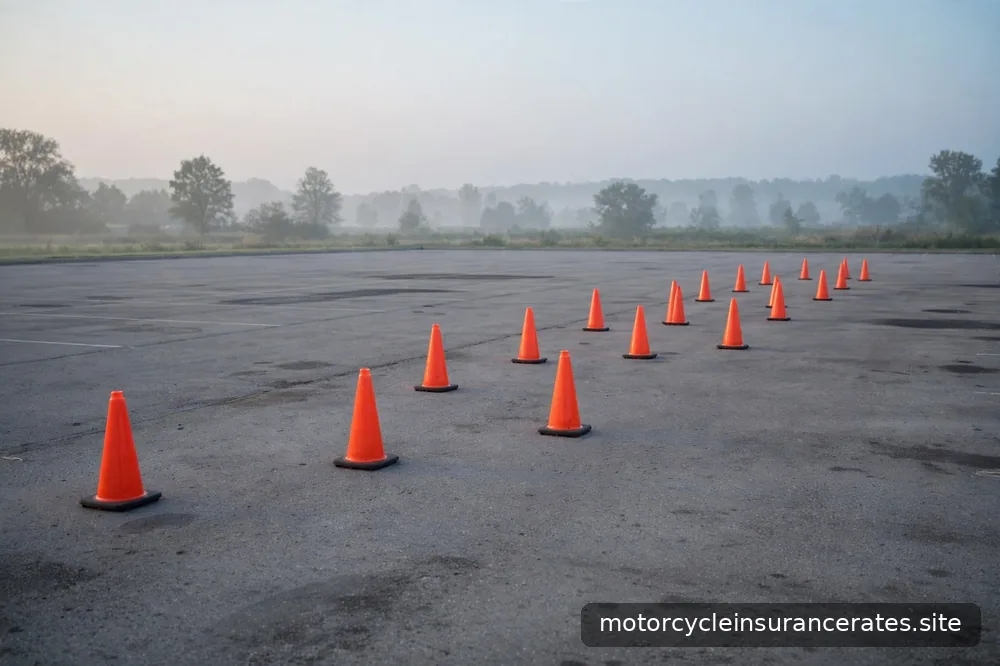
Range instruction puts you on a motorcycle in a controlled, closed lot. You’ll practice clutch and throttle control, starting and stopping, turning, weaving, quick stops, and swerving — the physical fundamentals, drilled repetitively under instructor supervision. Training bikes are typically provided, so you can learn before you own.
The course usually runs over a weekend — roughly a full two days, though formats vary by training site. At the end, riders who complete the course receive a completion card. That card is the document insurers may ask about — and the document licensing agencies may accept.
Two things worth knowing upfront: the BRC teaches you to operate a motorcycle safely, not to ride like an expert — it’s a foundation, not a finishing school. And quality is consistent by design: the MSF curriculum is standardized, taught by certified RiderCoaches, which is part of why insurers take it seriously as a signal.
Why insurers care about training
Insurers are in the business of predicting claims, and training is one of the few positive signals a new rider can send. The logic is straightforward:
Trained riders crash less. Rider education teaches hazard recognition and emergency maneuvers — exactly the skills that prevent the most common new-rider crashes (overshooting curves, panic braking, intersection errors). An insurer looking at two otherwise identical new riders will bet, correctly on average, that the trained one files fewer claims.
Training signals seriousness. Completing a weekend course is a costly signal in the economic sense — it takes time, money, and effort. Riders willing to invest that in safety tend to be the riders who take riding seriously generally. Insurers’ data picks up the correlation even if the mechanism is partly attitude rather than skill.
It’s verifiable. Unlike “I’m a careful rider” — which everyone claims — a completion card is a document. Insurers love documents. It’s the same reason they ask about garaging (verifiable) rather than “do you park carefully” (not).
This is also why the training benefit compounds: the course makes you safer (fewer crashes), the completion card improves your rating factor (lower premium), and the skills protect your record (clean history, which is itself a rating input). It’s one of the rare moves in insurance that’s genuinely win-win-win. Our young riders guide puts training in context as the single highest-leverage move a new rider can make.
The honest truth about the discount
Now the part the folk wisdom glosses over. Here’s what’s real and what isn’t:
Real: many insurers offer a training-related credit. It’s a common discount category — you’ll find “safety course” or “rider training” on many insurers’ discount lists, and many riders do pay less after completing the BRC.
Not real: universality. Not every insurer recognizes training. Some companies’ rating formulas simply don’t include it. If yours doesn’t, the course still made you safer — but it won’t move your premium at that company.
Not real: a fixed percentage. There is no industry-standard “10% MSF discount.” The credit varies by insurer and by state — different companies, different amounts, different application methods (some as an explicit discount, some baked into the rating factor). Any article stating a specific percentage as fact is describing one company’s deal, or inventing one.
Not real: automatic application. In most cases you have to tell your insurer you completed the course and provide the completion card. Insurers don’t monitor training registries. If you took the course and never told your insurer, you may be leaving the credit unclaimed right now.
Not real: permanent. Training credits typically apply for a set period — often a few years — after completion. They can expire, at which point refresher or advanced courses may renew the signal. Ask your insurer about the duration when you ask about the credit.
The pattern here is the same one that runs through all of motorcycle insurance: the direction is consistent (training helps), the magnitude is company-specific. If you’re new to the subject, our plain-English guide to what motorcycle insurance is builds the full picture from the ground up.
The license-test waiver: a separate benefit
Independent of insurance, BRC completion carries a practical licensing benefit in many states: presenting your completion card can waive the on-bike skills test at the DMV when you get your motorcycle endorsement. You still take the written test, but you skip the parking-lot exam.
The key phrase is “in many states” — not all. Waiver rules are set state by state, and they change. Some states waive the skills test, some waive it only for certain course providers, and a few don’t offer waivers at all. Check your state’s DMV site for the current rule before counting on it.
Even where the waiver exists, don’t treat the course as merely a license shortcut. Riders who take the BRC only to skip the test and then never practice are the ones who become statistics. The waiver is a convenience; the training is the point.
What to confirm before you enroll
A ten-minute call before you sign up prevents disappointment. Ask your insurer:
Do you recognize the MSF Basic RiderCourse (or my state’s approved equivalent) for a discount or rating credit? Get a yes or no.
Which courses qualify? Some insurers accept only specific programs. If you’re considering a non-MSF course, verify it counts.
How is the credit applied, and how much is it? Discount vs. rating factor, and the actual amount at your company in your state.
How long does the credit last? Know the expiration so you can plan refresher training.
What documentation do you need? Usually the completion card — ask whether a copy suffices and where to send it.
Does it apply to all bikes on my policy, or per-rider? In multi-rider households, know whose training counts for what.
And ask the training provider: the schedule, what’s provided (bikes, helmets), the cancellation policy, and whether the completion card they issue is the MSF card or a state-equivalent document. Then verify that document is the one your insurer asked for. A small amount of administrative diligence protects a weekend-sized investment of your time.
Beyond the BRC: continuing training
The BRC is a beginning. Riders who keep training keep the safety — and sometimes the rating — benefits compounding:
Intermediate and advanced courses (MSF’s own advanced offerings and equivalents) build on BRC fundamentals: higher-speed maneuvering, advanced braking, street strategies.
Track-based schools teach machine control at speeds and lean angles the street never should — in a controlled environment, with professional instruction. (Note: standard insurance typically excludes track riding itself — the training value transfers to the street; the coverage doesn’t transfer to the track.)
Dirt riding is arguably the best crash-avoidance education available — learning to slide, recover, and read traction on dirt teaches bike control that street-only riders never develop.
Each layer of training makes you a lower-risk rider in reality, which is what ultimately drives your long-term insurance costs down through the mechanism that matters most: not crashing. The discount is a nice acknowledgment; the skill is the actual asset.
If you’re weighing the course against its cost, also weigh it against the cost of the crash it might prevent — and against the other honest ways riders lower their costs, where training sits at the top of the list for good reason.
Frequently asked questions
How much is the MSF discount, exactly?
There is no exact industry-wide figure — it varies by insurer and state. Your insurer’s answer is the only one that matters for your policy. Anyone quoting a universal percentage is oversimplifying.
I took the course years ago. Does it still count?
Possibly not — training credits often expire after a set period. Check with your insurer; a refresher or advanced course may renew the credit.
Does the course help if I’m an experienced rider?
The rating credit may still apply, and the skills genuinely transfer — advanced courses are designed for exactly this. Experience without recent training still leaves rust.
Can I take an online course for the discount?
Classroom-only or online components generally don’t earn the riding-credit — insurers recognize the on-bike training. Verify with your insurer which formats qualify before paying.
Is the BRC hard to pass?
It’s designed for true beginners — most students with no experience complete it. The difficulty is appropriate: it should challenge you enough to actually teach you something.
Your concrete next step
Call your insurer this week and ask the six questions above — especially whether they recognize the BRC and what documentation they need. Then find your nearest training provider through the MSF’s course locator and book a date. The call takes ten minutes; the course takes a weekend; the benefits last for years.
Motorcycle Insurance Compass publishes general educational information about insurance. Nothing here is insurance, legal, or financial advice for your situation. Discounts and course recognition vary by insurer and state — talk to a licensed agent about your specific needs.