Everyone wants to pay less for motorcycle insurance, and the internet is full of advice — some of it good, some of it myth. This is the myth-free version: nine legitimate levers, each with its trade-offs stated plainly and its “verify this” caveats included. No invented discount percentages, no gimmicks, no advice to underinsure yourself into danger.
Key takeaways
- Savings come from levers, not loopholes. Training, garaging, deductibles, and shopping are real; “tricks” usually aren’t.
- Every lever has a trade-off. Higher deductibles, dropped coverages, and storage options all move risk back to you — understand what you’re accepting.
- Discounts vary by insurer and state. Any specific percentage you read online is someone else’s deal, not a promise.
- The biggest lever is the bike you buy. Class and displacement decisions dwarf most post-purchase tweaks.
- Shop with identical coverage. A cheaper quote with thinner coverage isn’t savings — it’s a different product.
On this page
- 1. Take a recognized safety course
- 2. Garage the bike
- 3. Bundle with your other policies
- 4. Raise your deductibles — carefully
- 5. Keep your record clean
- 6. Pay in full instead of monthly
- 7. Use lay-up or storage coverage in the off-season
- 8. Reconsider collision on low-value bikes
- 9. Shop with identical limits
- Frequently asked questions
- Your concrete next step
1. Take a recognized safety course
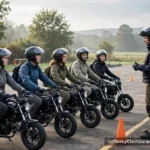
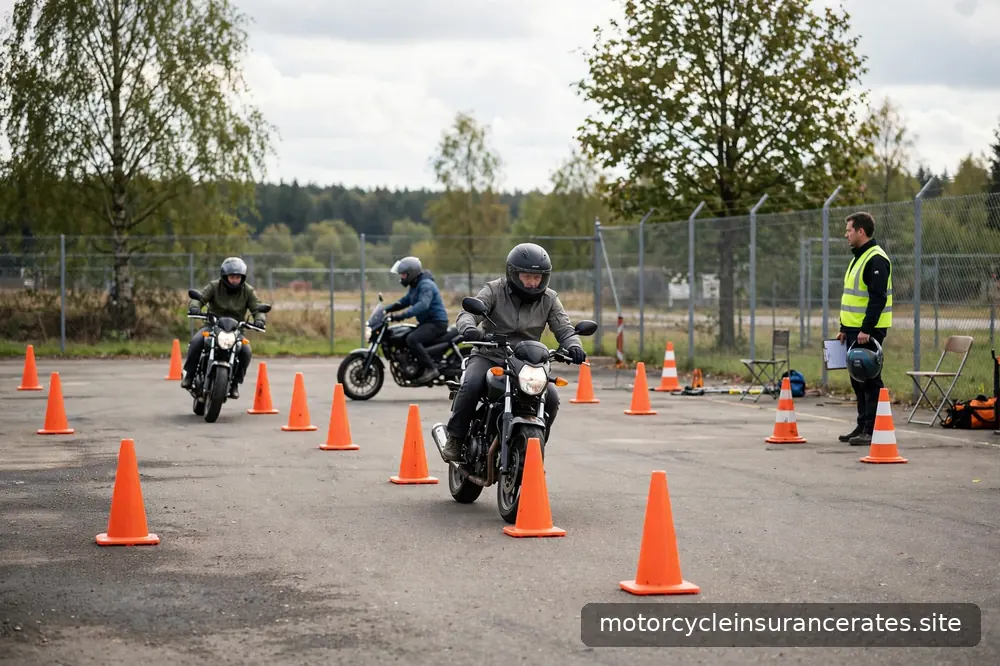
Completing a recognized rider training course — the MSF Basic RiderCourse or your state’s approved equivalent — is one of the few moves that can both make you safer and improve your rating profile. Many insurers recognize training with a discount or a favorable rating factor.
The honest caveats: recognition is not universal, and no fixed discount percentage exists across the industry — it varies by insurer and state. Confirm with your insurer before enrolling, and ask exactly what the course needs to be (some insurers only recognize specific programs) and how the credit is applied. Our MSF course deep-dive separates the real benefits from the assumed ones.
Also note the non-discount value: training genuinely reduces crash risk, and fewer crashes mean fewer claims — which is the deepest long-term savings mechanism of all. The course pays twice: once in the rating factor, once in the skills.
2. Garage the bike
Where the bike sleeps is a real rating input, driven mostly by theft and vandalism exposure. A locked garage rates better than a carport; a carport rates better than street parking. If you have access to a garage and aren’t using it for the bike, moving it inside is one of the fastest legitimate improvements you can make — sometimes effective at your next policy change.
If a garage isn’t available, a storage facility can be a middle option worth asking about — and whatever your situation, tell your insurer the truth about it. Misrepresenting garaging to get a better rate is misrepresentation, and it can poison a claim. The discount for honesty is that your coverage actually works when you need it.
3. Bundle with your other policies
Insuring your motorcycle with the same company that holds your auto or homeowners/renters policy often earns a multi-policy discount. Insurers like bundled customers — they’re stickier and simpler to serve — and they price accordingly.
Caveats: the discount exists at most insurers, not all, and its size varies. More importantly, bundling is only savings if the underlying motorcycle rate is competitive. A 10% bundling discount on an overpriced base policy still loses to a fairly priced standalone policy. Always compare the bundled total against standalone alternatives with identical coverage — loyalty should be verified, not assumed.
4. Raise your deductibles — carefully
Your collision and comprehensive deductibles are a dial: higher deductible, lower premium. You’re retaining more small-loss risk yourself, and the insurer charges less for the remaining risk.
The “carefully” matters. The right deductible is the highest amount you could pay tomorrow, from savings, without hardship — after a crash, when you’re also dealing with everything else a crash brings. A deductible you can’t actually pay is a false economy that turns a repairable bike into a financial crisis.
A practical way to think about it: if the premium savings from raising your deductible from $500 to $1,000 would take five claim-free years to equal the extra $500 you’d owe in a crash, the math favors the higher deductible only if you genuinely believe you’ll go five years without a comp/collision claim. That’s a judgment call about your risk, not a universal answer.
5. Keep your record clean
This is the slowest lever and the most powerful one. Violations and at-fault accidents raise rates because they predict future claims — and a clean record, compounding year after year, is what produces the deep rate decreases experienced riders enjoy.
There’s no shortcut here, but there are two honest accelerants:
- Ride like your record is being watched — because for rating purposes, it is. Every ticket avoided is money kept.
- Let time work. Old violations age out of rating eventually (timelines vary by insurer and state). Each clean year dilutes the last bad one.
And the defensive version: if you do get a ticket, look into your state’s options honestly — some states offer defensive-driving courses that can mitigate points, though the insurance effect varies. Ask, don’t assume.
6. Pay in full instead of monthly
Many insurers charge installment fees for monthly billing — small per-payment fees that add up over a policy term. Paying the premium in full upfront avoids them entirely. It’s not a “discount” in the marketing sense; it’s the absence of a fee.
The math is simple: if monthly billing adds a few dollars per installment, that’s real money over six or twelve payments. If cash flow makes pay-in-full hard, this lever may not be for you — and that’s fine. It’s a convenience trade-off, not a moral one. But if you can pay upfront, there’s rarely a reason not to.
7. Use lay-up or storage coverage in the off-season
If you live where winter parks the bike for months, you may not need full riding coverage year-round. Many insurers offer lay-up or storage options: keep comprehensive (theft, fire, falling objects — the perils that don’t care that you’re not riding) while suspending or reducing collision and liability for the storage months.
The trade-offs are real and worth stating: you cannot ride the bike at all while lay-up terms apply (a “quick spin” on a nice February day is uninsured riding); if the bike is financed, your lender almost certainly requires continuous full coverage and won’t allow lay-up; and cancelling outright instead is usually worse — it creates a coverage lapse and leaves the bike exposed to non-riding perils.
Our seasonal storage guide walks through the options and the spring reactivation checklist in full. The key principle: reduce coverage for storage, don’t abandon it.
8. Reconsider collision on low-value bikes
Collision coverage protects the bike’s value — and on an older, low-value bike, the math can stop making sense. If your bike’s book value is modest and your collision premium plus deductible approaches a large fraction of that value, you’re paying a lot to protect a little.
This is a judgment call, not a rule. Consider dropping or skipping collision when: the bike’s value is low, you could replace it out of savings without hardship, and you understand you’re self-insuring the bike’s damage. Keep it when: the bike is financed (lenders require it), the value is significant to you, or losing the bike would be a financial blow.
What you should not do is drop liability — liability protects other people and is legally required in most states — or drop comprehensive lightly, since comprehensive is usually inexpensive relative to the theft and weather protection it provides. And never let this decision be driven by a desire for the lowest headline premium; drive it by the value-at-risk math.
9. Shop with identical limits
The most underused savings lever isn’t a discount at all — it’s comparison. Insurers’ rating formulas differ, so the same rider and bike get different prices from different companies. The spread can be substantial.
The method matters more than the effort:
- Identical coverage, every quote. Same liability limits, same deductibles, same add-ons. A cheaper quote with thinner coverage isn’t savings.
- Same inputs, honestly given. Bike, garaging, mileage, record — identical and truthful everywhere.
- Compare the declarations, not the headline. Read what each quote actually covers before comparing prices.
- Re-shop periodically. Your profile changes (age, experience, record aging), and insurers’ formulas change. A company that was the lowest-priced option two years ago may not be today.
Shopping doesn’t cost anything but time, it doesn’t obligate you to switch, and it’s the only way to know whether your current price is competitive. Our guide to how rates are calculated gives you the input vocabulary to shop intelligently.
Frequently asked questions
What’s the single biggest way to lower my motorcycle insurance?
For most riders, it’s the bike choice itself — class and displacement dwarf post-purchase tweaks. After purchase, the biggest levers are usually garaging, deductibles, training, and shopping the market.
Do all these discounts stack?
Generally yes — multi-policy, paid-in-full, safety course, and garaging credits can all apply to the same policy. But each insurer’s discount menu differs, so “stacking” is company-specific.
Will taking the MSF course guarantee me a discount?
No — and anyone who guarantees it is oversimplifying. Many insurers recognize training, but it’s not universal and the amount varies. Confirm with your insurer before enrolling.
Is it ever smart to drop to liability-only?
It can make sense on a low-value, owned-outright bike where you can absorb the bike’s loss — but never drop liability itself, and think carefully before dropping inexpensive comprehensive. It’s a value-at-risk decision, not a savings hack.
How often should I shop for better rates?
At least every year or two, and after any profile change — a birthday that moves your age band, a violation aging off, a move, a new bike, completing a safety course. The market moves; check whether it moved in your favor.
Your concrete next step
Pick two levers from this list you haven’t pulled — the best candidates for most riders are garaging (if fixable) and shopping three quotes with identical coverage. Do both this month. Then put a recurring calendar reminder to re-shop annually. Savings in motorcycle insurance compound like interest: small, regular, and in your favor.
Motorcycle Insurance Compass publishes general educational information about insurance. Nothing here is insurance, legal, or financial advice for your situation. Discounts and rating factors vary by insurer and state — talk to a licensed agent about your specific needs.