How Motorcycle Insurance Works: From Premium to Payout
Premium in, payout out — but what happens between? This walkthrough follows one hypothetical motorcycle claim from the crash scene through investigation to settlement, explaining premiums, deductibles, limits, and fault along the way.
Motorcycle insurance works like this: you pay a premium for a contract, and if a covered crash happens, the insurer investigates and pays up to your policy’s limits — minus your deductible on the bike-repair parts. Fault decides whose policy pays whom. The whole system runs on four numbers: premium, deductible, limit, and fault.
Key takeaways
Premium is the price of the promise; the policy is the promise. You pay regularly, the insurer agrees to pay for covered losses up to stated limits.
Deductible applies to your bike, not to other people. Collision and comprehensive payouts subtract your deductible; liability payouts to others don’t have one.
Fault decides direction. Your liability pays others when you’re at fault; their liability (or your UM/UIM) pays you when they’re at fault.
The insurer investigates before it pays. Adjusters verify coverage, fault, and damage — the check doesn’t go out on day one.
Settlement ends with either repair, book-value payment, or a liability settlement — each with its own math.
Every motorcycle insurance interaction — buying, claiming, renewing — runs on four numbers. Learn them once and the rest of the system reads like plain English.
Premium is what you pay for the policy — monthly, quarterly, or annually. It’s the price of the insurer’s promise, calculated from your rating factors: bike type, age, record, location, garaging, mileage, coverage choices. Pay it and the promise stays live; stop paying and it lapses.
Deductible is what you pay out of pocket before the insurer pays on your bike’s repairs — and only there. Choose a $500 deductible on collision, and a $3,000 repair estimate becomes a $2,500 insurer check. Deductibles apply to collision and comprehensive. They do not apply to liability payments to other people: if your liability pays an injured driver, no deductible comes out of their payment.
Limit is the maximum the insurer will pay for a covered claim. Liability limits cap what goes to others; UM/UIM limits cap what comes to you. The limit is the number that matters most on the declarations page, and it’s the number beginners look at least.
Fault is the direction arrow. It answers: whose insurance pays whom? In most states, the at-fault rider’s (or driver’s) liability pays the injured party. Fault is decided by evidence — police reports, statements, photos — not by who feels worse about it.
Premium buys the contract. Deductible splits the bike-repair bill. Limit caps every payment. Fault aims the money. Keep those four straight and claim stories stop sounding like mysteries.
If the vocabulary around those numbers feels shaky, our cornerstone what motorcycle insurance is explains which coverages those numbers attach to.
A hypothetical claim, start to finish
The cleanest way to understand the system is to watch it run. Here’s a hypothetical crash — every figure illustrative, every step real in structure.
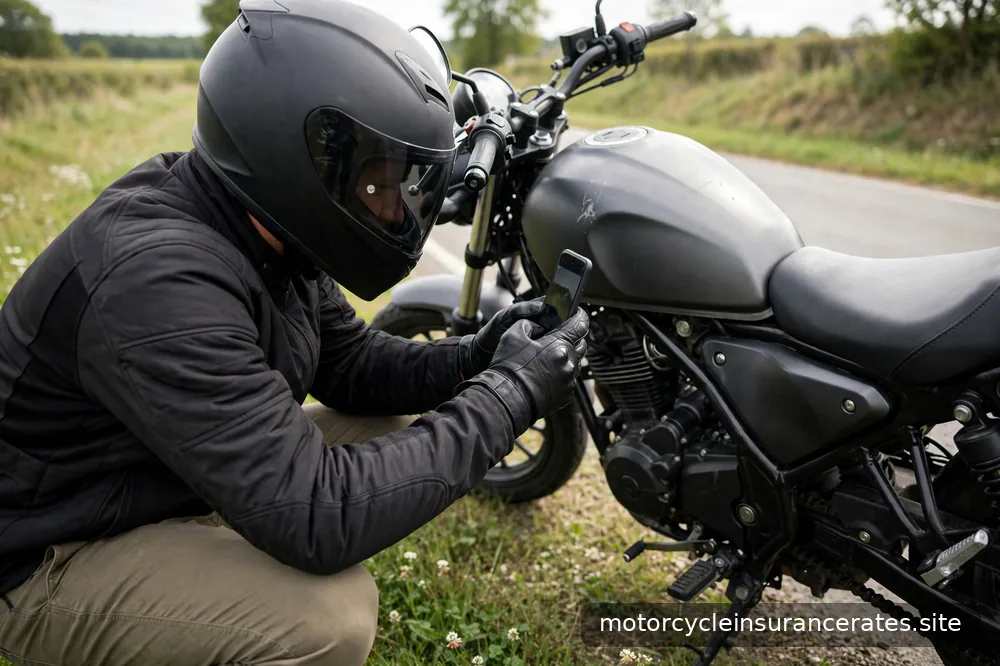
The incident. You’re riding home on a Saturday afternoon when a driver turning left across your lane misjudges your speed and turns into your path. You brake hard, go down, and your bike slides into the car’s quarter panel. You’re hurt — broken collarbone, road rash — and both vehicles are damaged. A witness saw it; police file a report.
Notice. Once you’re able, notify your insurer — most policies require prompt notice, so don’t let “when you’re able” stretch into weeks. Report the basics: when, where, who, what happened, the other driver’s info, the police report number. Your insurer opens a claim file and assigns an adjuster.
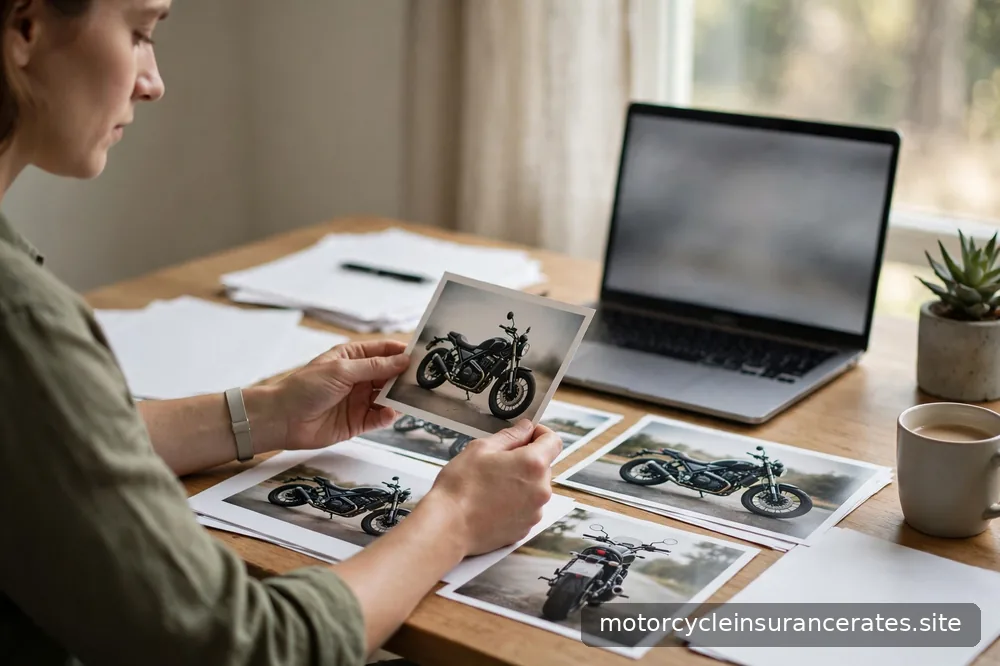
The investigation. This is where claims actually get decided. The adjuster collects the police report, both statements, the witness account, and photos — answering three questions in order: (1) Is this covered? (2) Who was at fault? (3) What’s the damage worth?
Fault determination. The evidence points one way: the turning driver failed to yield. In most states, that driver’s liability becomes the paying policy — for your injuries, lost wages, and bike. (No-fault states handle the first layer differently, but the investigation is the same.)
The two payouts. Your claim splits in two. The bike goes through property damage: the at-fault driver’s liability pays to repair it (or pays book value if totaled). Your body goes through bodily injury: their liability pays your medical bills and lost wages, up to their limit. If their limits run out first, your own UM/UIM — if you carry it — can cover the remainder, up to your UM/UIM limit.
Settlement and close. Once the bike is appraised and your treatment stabilizes, the insurer makes offers, you accept or negotiate, payments go out, and the file closes. Incident to closed file: typically weeks for property damage alone, months with injuries. That’s normal.
What the adjuster actually does
The adjuster is the insurer’s fact-finder — not your adversary, not your advocate. Understanding the job makes the process less stressful.
Coverage check first. The adjuster confirms the policy was active on the crash date, the premium was paid, and the loss fits the coverage. A lapsed policy or excluded use (racing, delivery work on a personal policy) can end a claim right here.
Liability investigation. The adjuster reconstructs fault from police reports, statements, witnesses, photos, sometimes camera footage — weighing evidence, not taking anyone’s word. Where fault is shared, many states split it by percentage, reducing each side’s payment proportionally.
Damage appraisal. An appraiser estimates repair cost against the bike’s pre-crash book value. If repairs approach that value (threshold varies by insurer and state), the bike is totaled and the payout becomes book value instead. For injuries, the adjuster reviews medical records — which is why consistent, documented treatment beats toughing it out.
Reserves. Early on, the adjuster sets a “reserve” — the insurer’s internal cost estimate. Not an offer, not public — but it explains why a first offer sometimes arrives faster than expected.
Good scene habits help both of you: photos of everything, the other party’s insurance info, witness names, a police report whenever anyone’s hurt or fault could be disputed. Our how to file a motorcycle insurance claim guide turns those into a phone-ready checklist.
How the payout is calculated
Payout math differs by which part of the policy is paying. Three formulas cover nearly everything:
Your bike, your collision or comprehensive: payout equals book value before the loss (or repair cost, whichever is lower) minus your deductible. Illustrative: $8,000 book value and a $500 deductible means a $7,500 check — the structure is exact even though the numbers are hypothetical. Note what’s missing: custom exhaust, saddlebags, paint — the valuation covers factory equipment unless you carry custom parts coverage.
Your bike or injuries, someone else’s liability: their property-damage liability pays your bike’s repair or book value (no deductible — deductibles are first-party only), and their bodily-injury liability pays medical bills and lost wages, up to their limits. Losses beyond their limits are legally the at-fault party’s personal problem — which is exactly why your own UM/UIM exists.
Your injuries, your UM/UIM: mirrors the liability math above, but paid by your own insurer stepping into the uninsured driver’s shoes, up to your UM/UIM limit.
One wrinkle: if you financed the bike and it’s totaled, the payout goes to the lender first. Owe more than book value — common early in a loan — and the gap is yours unless you carry gap coverage.
Which of your coverages handles the bike comes down to collision vs. comprehensive. Our comparison runs the scenarios — crash, theft, hail — and shows which answers each.
Where claims get stuck
Most claims that stall do so for a handful of predictable reasons — and most are preventable.
Late notice. Waiting weeks gives the insurer contractual room to question the claim. Report as soon as you’re able.
Thin documentation. No photos, no witnesses, no police report, gaps in treatment — every gap is something the adjuster guesses at, and guesses don’t favor claimants.
Disputed fault. Different stories plus thin evidence means a long investigation — the most common reason simple claims take months. A police report and a witness beat any argument.
Coverage questions. Was the policy active? Was the bike being used as covered? Was the rider listed or excluded? Any “no” here can reduce or deny the claim — which is why reading the exclusions before a crash matters.
Ongoing treatment. Insurers won’t settle the injury portion until treatment stabilizes — nobody knows the final bill yet. That’s arithmetic, not stonewalling. Property damage can usually settle meanwhile.
Low limits on the other side. Minimum limits plus big bills makes the math adversarial. Your UM/UIM is the safety net — if you bought it.
What happens to your policy afterward
Filing a claim doesn’t end the story — it writes the next chapter of your policy.
Your premium at renewal. An at-fault accident can raise your premium — how much and for how long varies by insurer and state. Not-at-fault claims are treated more leniently, but there’s no universal rule. Expect your record to matter for several years.
Your insurer relationship. One claim rarely triggers non-renewal. A pattern — multiple at-fault accidents plus violations — can. Insurers may decline risks they don’t want, within state rules.
Your next shopping trip. After a claim, compare with identical limits — it’s also when riders discover what their UM/UIM limits actually were. Many raise them then; make that call with an agent.
The usual lesson. Nearly every rider says the same thing after a claim: they finally read their policy. Reading it before the next incident takes twenty minutes and works strictly better.
Frequently asked questions
How long does a motorcycle insurance claim take?
Simple property-damage-only claims often resolve in weeks. Claims involving injuries typically take months, because settlement waits until medical treatment stabilizes and the full cost is known. Disputed fault adds time in either case.
Do I have to use the repair shop my insurer suggests?
In most states the choice is yours; insurers may suggest network shops, but you can pick your own. The insurer pays the appraised reasonable cost either way.
Will my rates go up if I file a claim that wasn’t my fault?
Not-at-fault claims are treated more leniently in most rating systems, but there’s no universal rule — it varies by insurer and state. At-fault surcharges are what reliably move premiums.
What if the other driver has no insurance?
Your collision coverage (if you carry it) can handle your bike, and your UM/UIM (if you carry it) handles your injuries and lost wages. Without those, you’re pursuing the uninsured driver personally — which is why UM/UIM is the coverage riders are most often glad they bought.
Can I settle the bike damage while my injury treatment continues?
Often, yes. Property damage and bodily injury are separate negotiations within the same claim file, and the bike portion can close while medical treatment is ongoing. Your adjuster can confirm how your insurer handles it.
Your concrete next step
Open your policy’s declarations page — one page, usually the first — and find four numbers: your liability limits, your collision deductible, your comprehensive deductible, and your UM/UIM limits. Write them on a card you keep with the bike. The next time anyone (including a future version of you) asks “what happens if I crash,” you’ll answer from your actual contract instead of from memory.
Motorcycle Insurance Compass publishes general educational information about insurance. Nothing here is insurance, legal, or financial advice for your situation. Policy language varies by insurer and state — read your own policy and talk to a licensed agent about your specific needs.