How to File a Motorcycle Insurance Claim: Step by Step
A calm, practical walkthrough of the motorcycle claim process: what to do at the scene, how to notify your insurer, what the adjuster does, how repair vs. total-loss decisions work, and when to consider legal counsel.
Filing a motorcycle insurance claim follows a predictable sequence: secure the scene and document everything, notify your insurer promptly, cooperate with the adjuster’s investigation, then resolve through repair or settlement. Knowing the sequence in advance keeps you from making the small early mistakes that complicate claims later.
Key takeaways
The scene is where claims are won or lost — photos, notes, and witness details gathered in the first hour matter more than anything you do later.
Notify your insurer promptly — policies require timely notice, and delays give the insurer legitimate questions about the claim.
The adjuster’s job is investigation, not advocacy — be cooperative, factual, and careful about recorded statements.
Repair vs. total loss is a math decision — when repair costs approach the bike’s value, the insurer totals it; understand how that valuation works.
You can ask questions at every stage — including when to consider consulting an attorney for injury claims.
Everything in this section assumes you are physically able to act. If you or anyone else is hurt, medical attention comes before all of it — no documentation is worth delaying care.
Make the scene safe. Move yourself out of traffic if you can do so safely. Turn on hazard lights if the bike has them. Set out warning triangles or flares if you carry them. A second collision at the same scene helps nobody.
Call the police. For anything beyond a trivial solo tip-over, get a police report — an official, timestamped record that becomes a foundation document for the claim. Some states legally require reporting above certain thresholds; when in doubt, call.
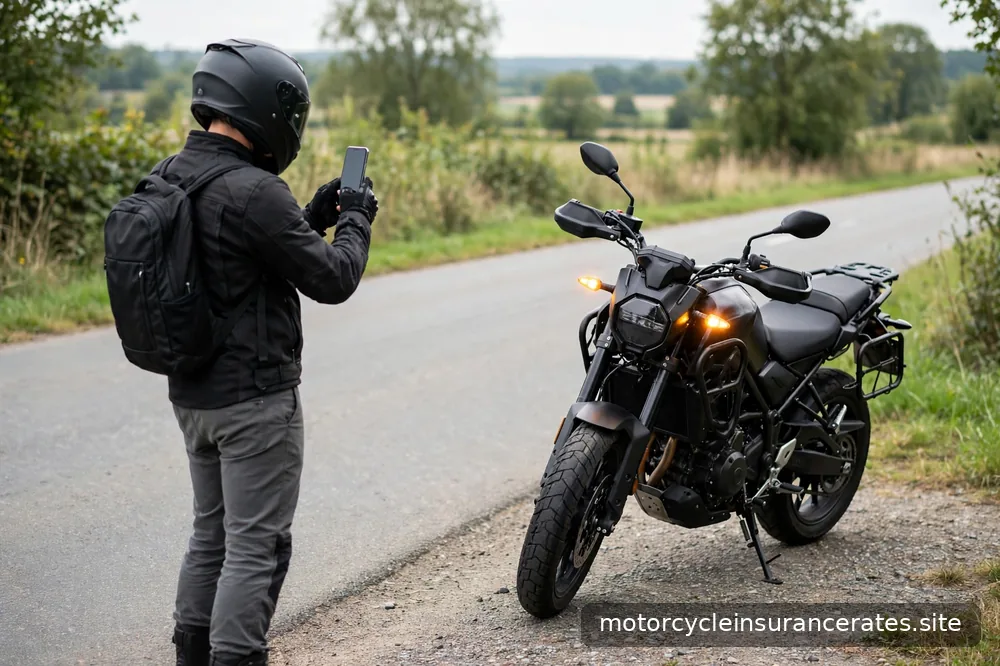
Document relentlessly. Your phone is your most powerful claims tool. Photograph the scene from multiple angles, all vehicle positions, damage (close and wide), road conditions and debris, your gear, and any visible injuries. Then write down what happened while it’s fresh — memory degrades fast, and scene notes beat week-old recollections.
Exchange information, not arguments. Get names, contacts, insurance info, plate numbers, and vehicle descriptions from every party — plus contact info for any witnesses. Don’t debate fault at the scene: “I’m sorry” can read as an admission. Be polite, be factual, leave fault to the investigation.
Note what not to move. If the situation allows safely, leave vehicles where they are until police arrive — final resting positions tell a story. If you must move for safety, photograph first.
The first 24 hours
Get medical evaluation even if you feel fine. Adrenaline masks injuries — concussions, internal injuries, soft-tissue damage can surface hours or days later. A same-day visit creates a record linking injuries to the incident; a two-week delay gives an insurer room to question the connection.
Preserve your gear. Don’t throw away a damaged helmet or torn jacket. Damaged gear is evidence — of the incident’s severity and, where you carry gear or accessory coverage, of a compensable loss. Store it as-is.
Don’t post about the incident on social media. Photos of the crash, commentary about fault, even check-ins at the track or the bar — all of it is potentially visible to an adjuster or opposing counsel. Stay quiet online until the claim resolves.
Start a claim file. Every incident document goes in one folder — police report number, photos, medical paperwork, towing and rental receipts, insurer correspondence. Organized riders resolve faster and miss less.
Review your policy. Before you call, know your deductibles and coverages — collision, comprehensive, uninsured motorist, medical payments, accessories, rental/towing. Walking in informed changes the conversation completely. If the terminology is unfamiliar, our walkthrough of how motorcycle insurance works explains the moving parts — premium, deductible, limits, fault — that the claims process runs on.
Notifying your insurer
Call promptly. Policies require “prompt” or “timely” notice of a claim or potential claim — the exact wording varies, but the principle doesn’t. Waiting weeks to report gives the insurer legitimate grounds to question the claim’s validity and complicates investigation (evidence goes stale, witnesses forget). Report within days, not weeks.
Know what the first call covers. The initial report is factual, not argumentative: when and where it happened, who was involved, what was damaged, whether police and medical responded, and your policy number. You’ll get a claim number — write it down; it’s the reference for everything that follows.
Understand who you’re talking to. The first call is usually with a first-notice representative, not your adjuster (assigned within a few business days). You don’t need your whole case ready.
If another driver was at fault, you have two paths. You can file with your own insurer (which then pursues the at-fault driver’s insurer — subrogation) or directly with the at-fault driver’s insurer. Your own insurer is usually faster, though you pay your deductible upfront and wait for recovery; the other insurer avoids your deductible but runs on their timeline.
Be careful with recorded statements. You may be asked for a recorded statement — normal, but permanent. Stick to firsthand facts, don’t speculate or guess at speeds and distances, and don’t minimize injuries (“I’m fine” on day one can haunt a legitimate claim on day thirty). With significant injuries, consider consulting an attorney before giving a statement to the other party’s insurer.
Working with the adjuster
The adjuster investigates and evaluates: what happened, what your policy covers, what the insurer owes. They’re not your advocate, but not your adversary by default — most friction comes from mismatched expectations.
The investigation. The adjuster reviews the police report, your statement, photos, and any witness accounts. For vehicle damage, they’ll arrange an inspection — either in person, at a shop, or increasingly via photos you submit through an app. For injury claims, they’ll review medical records (which you’ll authorize them to access). Cooperate fully and promptly; delays on your side extend the timeline.
The coverage determination. Before valuing anything, the adjuster confirms the loss is covered: policy in force, use covered (this is where exclusions get checked), facts fitting a covered peril. A denial should come in writing with the policy language cited — and you can question it or complain to your state’s department of insurance.
The valuation. For bike damage, the adjuster estimates repair costs from a shop estimate or inspection — a negotiation starting point, not a final decree. If a reputable shop’s estimate is higher, present it with documentation. Keep every incident receipt: towing, storage, rental.
Communication discipline. Log every interaction — date, person, what was said. Get important things in writing; email beats memory. Confirm verbal promises the same day.
Repair vs. total loss: how the decision works
At some point the adjuster — or you, with the numbers in front of you — faces the repair-vs.-total-loss question. Here’s the mechanics.
Total loss is a math threshold, not a damage description. A bike is declared a total loss when the estimated repair cost approaches or exceeds a set percentage of the bike’s actual cash value (the pre-incident market value). That percentage threshold varies by state and insurer — some states set it by law, others leave it to the insurer. Cosmetically devastating damage can be a repair; invisible frame damage can be a total. The label follows the arithmetic.
Actual cash value is the key number. Insurers pay the bike’s market value just before the incident — not what you paid or owe. That surprises riders who owe more than the bike is worth (gap coverage addresses this, where available) and riders with heavy customization — which is why documenting custom parts matters, as our guide to collision vs. comprehensive explains.
You can question the valuation. If the number feels low, research comparable bikes for sale nearby — same year, model, mileage, condition — and present them. Valuations run on comparable data; “I feel it’s worth more” moves nothing, but three comparable listings might.
If it’s repaired: choose the shop. You generally have the right to choose your repair shop, though the insurer may have preferred shops with streamlined processes. Get the choice in writing if there’s any ambiguity, and make sure the shop and adjuster agree on the scope before work starts — supplement disputes mid-repair are common and annoying.
If it’s totaled: know the settlement components. A total-loss settlement is typically actual cash value plus applicable taxes and fees, minus your deductible — with scheduled or documented custom parts included up to your accessory coverage limit.
Timelines: how long claims take
Simple property-damage claims with clear fault can resolve in days to weeks; disputed fault, injuries, or valuation disagreements can take months. Notes on timing:
Your responsiveness is the variable you control — answer document requests in a day, not a week.
Injury claims take longer than property claims, often substantially — partly because the full extent of injuries isn’t known early, and settling before it is known would be a mistake.
States regulate claim-handling timelines — most require insurers to acknowledge, investigate, and pay or deny within set timeframes. If a claim stalls without explanation, your state’s department of insurance is the escalation path.
Don’t let impatience accept a bad settlement — a settlement signed is a settlement final. For injury claims especially, patience is worth money.
When to consider legal counsel
Most straightforward property-damage claims don’t need a lawyer. But consider consulting one — most personal-injury attorneys offer free initial consultations — when:
You’ve been injured, especially seriously. Injury valuation (medical costs, lost wages, pain and suffering concepts) is where insurer and claimant interests diverge most sharply.
Fault is disputed and significant money is at stake.
The other party’s insurer contacts you asking for statements or offering quick settlements. Their adjuster works for them, not you.
Your own insurer denies coverage and you believe the denial misreads the policy.
A government entity or commercial vehicle is involved, which can trigger special procedures and deadlines.
This isn’t advice to hire a lawyer for every claim — it’s a map of when the consultation is worth having. Consult early, before recorded statements or accepted offers; timing preserves options.
One more honest note: how a claim resolves can affect what you pay next. At-fault accidents and claims history feed into future premiums — our guide to what raises motorcycle insurance rates explains the mechanics, so there are no surprises at your next renewal.
Frequently asked questions
How soon after an incident must I file?
Report within days — sooner is better: evidence is fresh, witnesses reachable. Don’t wait until the bike is fixed or injuries fully diagnosed to make the first call.
Will filing a claim raise my rates?
Possibly — it depends on fault, your insurer’s practices, your state, and your history. Not-at-fault claims are treated more leniently, but “more leniently” isn’t “invisibly.” Ask your agent before assuming.
Can I choose my own repair shop?
In most states, yes. Insurers may suggest preferred shops, but steering you to a specific shop against your will is restricted or prohibited in many states — ask your state’s department of insurance if you feel pressured.
What if the other driver has no insurance?
This is what uninsured/underinsured motorist coverage exists for — your own policy steps in where the at-fault driver’s missing coverage leaves a gap. Without UM/UIM, you’re left pursuing the other driver’s personal assets, often a dead end.
The insurer’s valuation seems low. What can I do?
Gather comparable listings (same year/make/model/mileage), document your bike’s condition and custom parts with receipts, and present the package in writing. If negotiation stalls, your policy may include an appraisal clause.
Should I accept the first settlement offer?
For property damage with a solid valuation, the first offer is often fair. For injury claims, rarely — the full picture isn’t known early, and early offers reflect that uncertainty in the insurer’s favor. Never sign a release until the settlement covers the full picture.
Your concrete next step
Do the boring preparation now: photograph your bike from all four sides (odometer and custom parts included), save the photos off your phone, and memorize your insurer’s claims number and policy number. Ten minutes today beats ten hours of reconstruction after an incident.
Motorcycle Insurance Compass publishes general educational information about insurance. Nothing here is insurance, legal, or financial advice for your situation. Policy language, claim procedures, and state rules vary — read your own policy and talk to a licensed agent or attorney about your specific needs.